Isaias damage in Miramar Beach or Sandestin?
Get prepared before you file.
High-rise condos, resort properties and beach homes need a careful claim. Get a free review from licensed Florida public adjusters before you call your insurance company.
- 5.0★ Google rating, 380+ reviews
- Licensed Florida public adjusters
- Local offices in Pensacola and Panama City Beach
- 5.0★Google rating from 380+ reviews
- $10B+Noble reports recovered for policyholders
- 10%Florida fee cap on emergency claims, first year
- 1 yrTo report a new hurricane claim in Florida
Miramar Beach
Your unit, your claim. Document it.
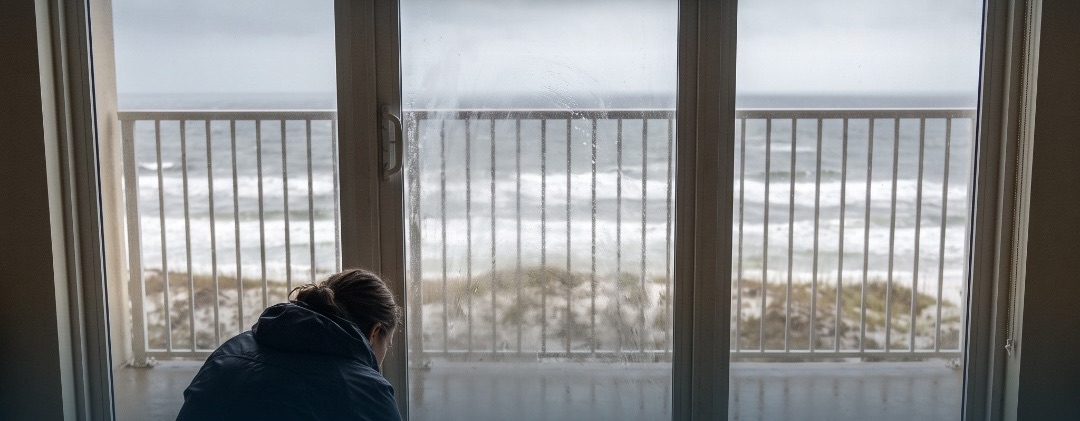
Water intrusion, balconies, interiors. Capture it all before anything gets cleaned up.
Before you file
Before you file your Hurricane Isaias claim in Miramar Beach
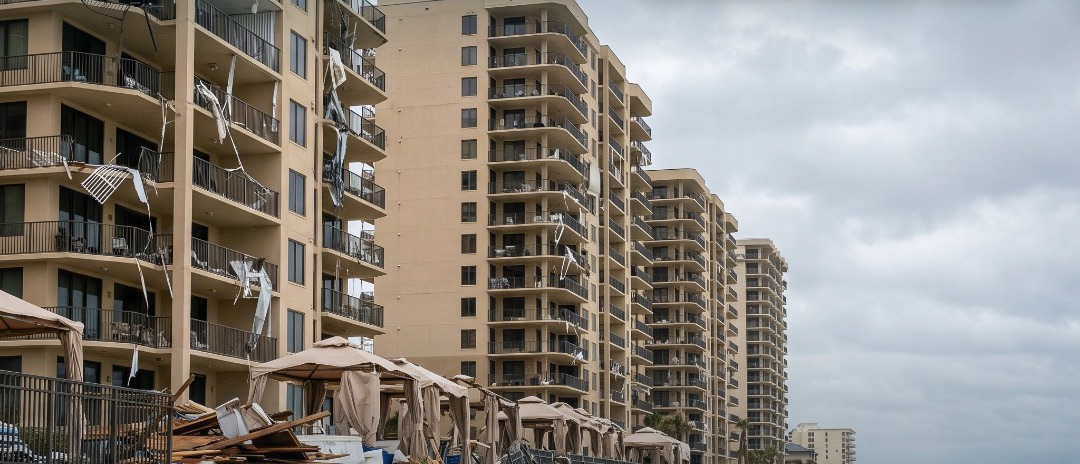
Miramar Beach and Sandestin are packed with high-rise condos, resort villas and gated beach homes, and that makes hurricane claims here more complicated than a typical single-family claim. Damage often crosses the line between what the association covers and what the owner covers.
After Hurricane Isaias, getting the documentation right from the start makes the biggest difference. Photos, a damage timeline, your association's insurance documents and your own policy all need to line up before you file.
Common Miramar Beach and Sandestin claims
In Gulf-front towers along Scenic Gulf Drive, the most frequent problems after a hurricane are window and sliding-door failures, water coming in through walls and balconies, and damage that spreads from one unit to the units below. In resort communities, owners also run into rental-program interruptions and shared-amenity damage.
Beach homes and villas set back from the water still see roof, soffit and siding damage from sustained wind, plus water intrusion that may not show up as stains or mold for days or weeks. Documenting moisture early helps.
Pre-filing checklist
6 things to do before you call your insurance company
Work through these in order. Step 6 is where we come in.
Get my free claim reviewStay safe and make temporary repairs
Tarp the roof, board openings and remove standing water to stop more damage. Keep every receipt. Reasonable emergency repairs are usually covered, and your policy expects you to prevent further damage.
Photograph and video everything before cleanup
Shoot every room, wall, ceiling, roof slope and outdoor structure. Get wide shots and close-ups, and narrate the video. Don't throw away damaged items until they're documented.
Find your policy and declarations page
You'll need your homeowners or condo policy, any separate flood policy, and the declarations page that shows your limits and hurricane deductible.
Start a claim diary
Write down every call, email and visit: date, time, name and what was said. Keep copies of everything you send and receive.
Gather proof of what you had
Old photos, receipts, bank statements and listing photos help prove the condition of your property and the value of your belongings before the storm.
Get a free claim review before you file
Report the loss as your policy requires, but talk to a licensed public adjuster before giving a recorded statement, signing anything or accepting an estimate.
Why Noble
Licensed Florida public adjusters who work only for you
Noble Public Adjusting Group represents homeowners, condo owners, associations and businesses, never insurance companies. Noble reports more than $10 billion recovered for policyholders.
“Insurance Co.'s offer: $9,708.34. Noble's Settlement: $21,797.13. John was able to increase the settlement by 224% in less than a month's time.”
“They did exactly what they said, they filed, they fought, they finished.”
“I interviewed several PA groups before choosing and thankful every day that I chose Noble. They were the most professional and knew everything what I needed to do.”
- JWJames "Bo" WilliamsonFounder & Owner
- VSValerie SasserDirector of Operations
- BMBenjamin MaxwellClaims Manager
- MGMarianne del GallegoLoss Estimating Manager
Pensacola office
3250 W Navy Blvd, Suite 101
Pensacola, FL 32505
Panama City Beach office
107 Amar Pl, Suite 103
Panama City Beach, FL 32413
Miramar Beach
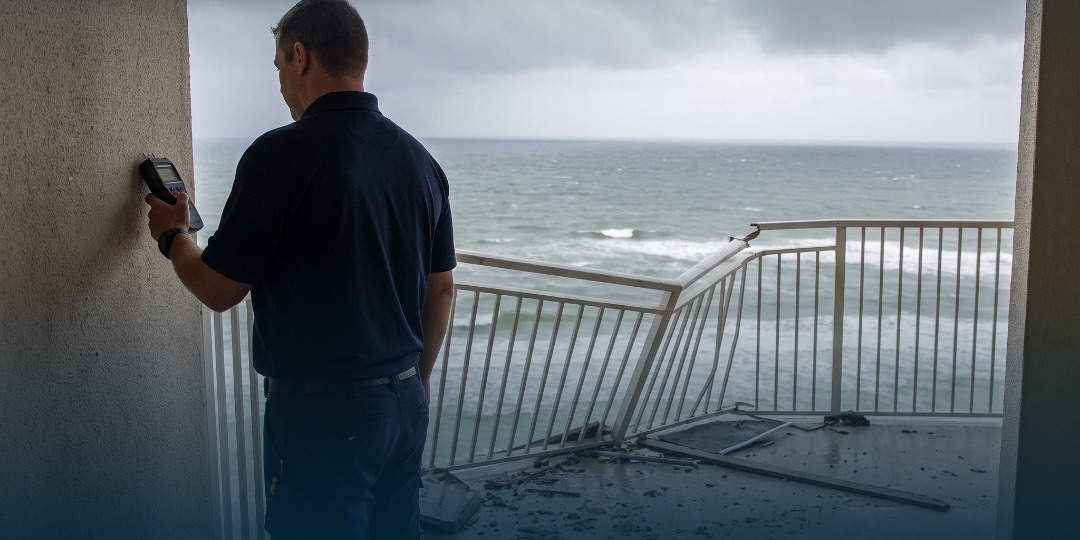
Free review, no upfront cost
Licensed Florida public adjusters who work for you, not the insurance company.
Florida law
Hurricane claim deadlines every Florida property owner should know
| What | Deadline | Source |
|---|---|---|
| Report a new or reopened hurricane claim | Within 1 year of the date of loss | Fla. Stat. 627.70132 |
| Report a supplemental claim (more damage found later) | Within 18 months of the date of loss | Fla. Stat. 627.70132 |
| Insurer acknowledges your claim communication | Within 7 days | Fla. Stat. 627.70131 |
| Insurer inspects after receiving proof of loss | Within 30 days | Fla. Stat. 627.70131 |
| Insurer pays or denies the claim | Within 60 days of notice | Fla. Stat. 627.70131 |
Deadlines current as of the 2026 Florida Statutes. Your policy may set additional duties, so read it carefully.
Questions
Hurricane Isaias claim questions: Miramar Beach
My Sandestin unit is in a rental program. Who files the claim?
Usually the association or resort files for the building and common areas, and you file your own unit policy claim for interior damage, contents and lost rental income if covered. Ask your rental program for any damage reports they've done, and keep copies.
Water came through my sliding doors but there's no visible roof damage. Is that covered?
Wind-driven rain is often covered when the wind created an opening, but policies treat it differently. Photos of the doors, frames and any debris or damage around the opening help show how the water got in.
What does a public adjuster do?
A licensed public adjuster works for you, not the insurance company. We inspect and document the damage, review your policy, prepare a detailed estimate, and negotiate with your insurer to get the full amount your policy owes.
How much does Noble charge for a Hurricane Isaias claim?
The claim review is free. If you hire us, our fee is a percentage of what your insurer pays. For claims from a declared state of emergency, Florida law caps public adjuster fees at 10% of claim payments during the first year after the declaration.
How long do I have to file my Hurricane Isaias claim in Florida?
Florida law requires notice of a new or reopened claim within 1 year of the date of loss, and a supplemental claim within 18 months. Report as soon as you safely can, because waiting can make damage harder to prove.
Service areas
Areas we're helping after Hurricane Isaias
Get prepared before you file.
A free claim review takes a few minutes and costs nothing.